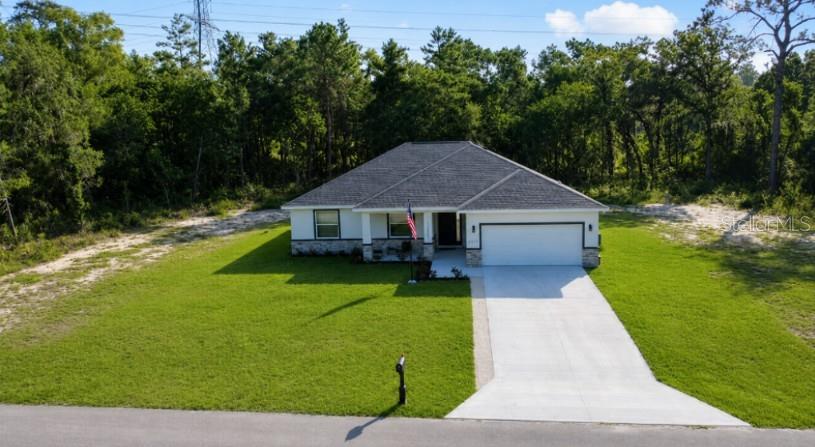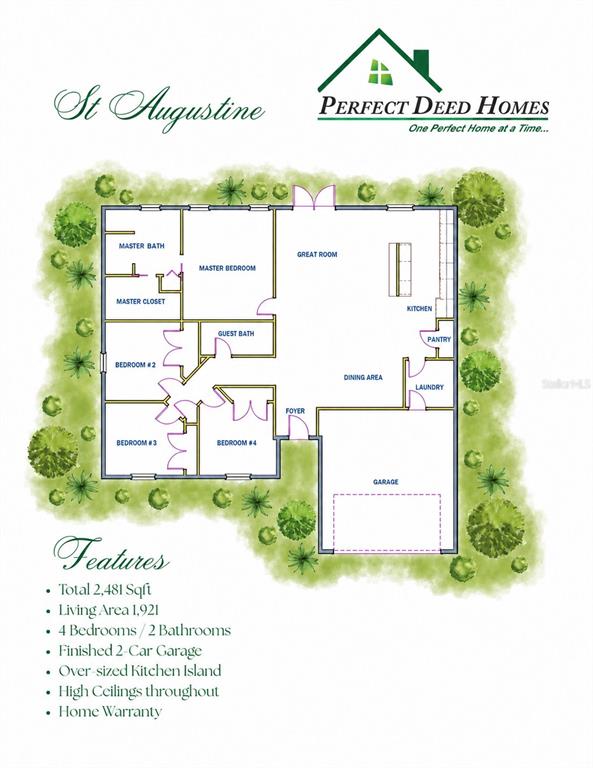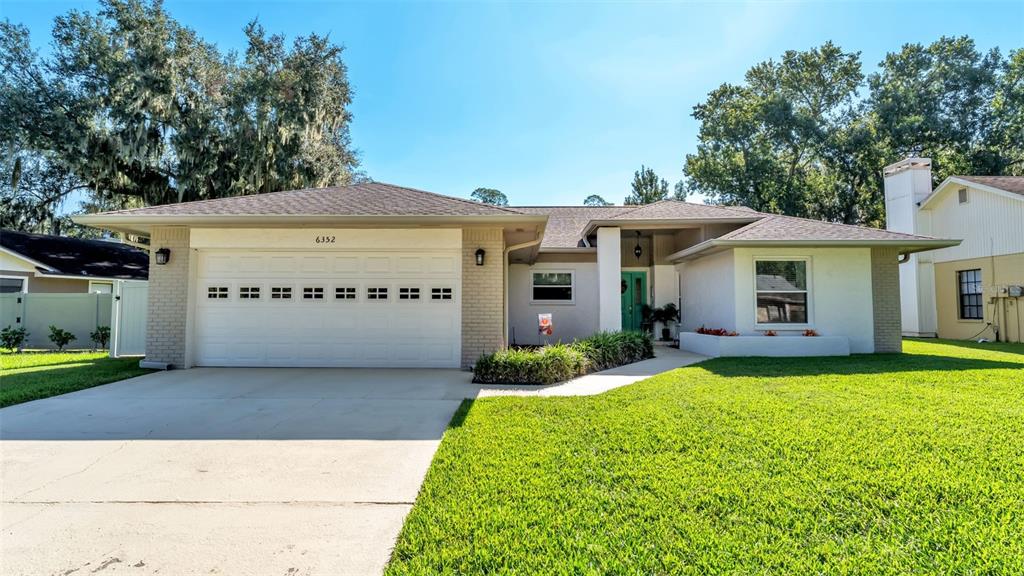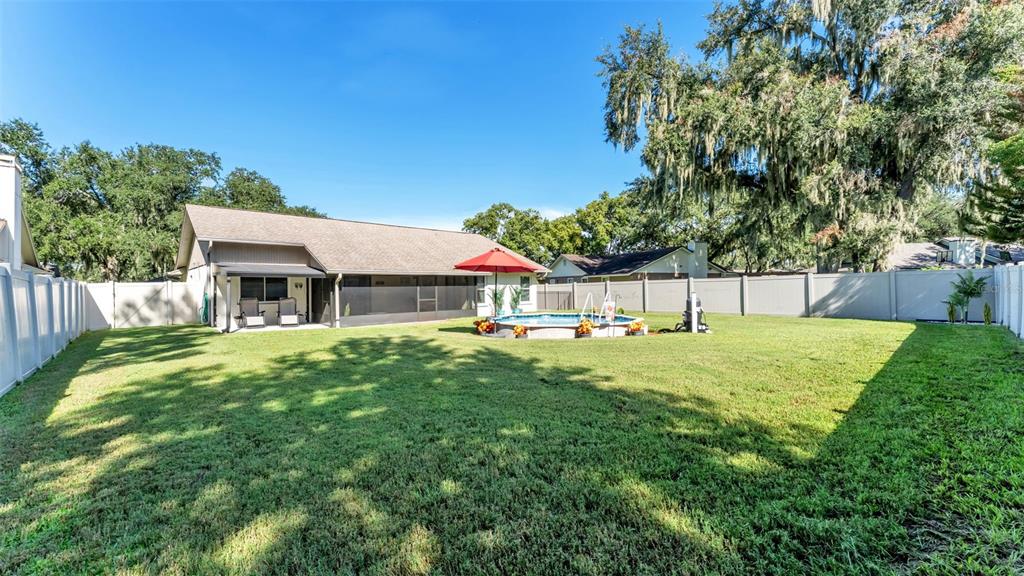
 1 day on market
$299,900
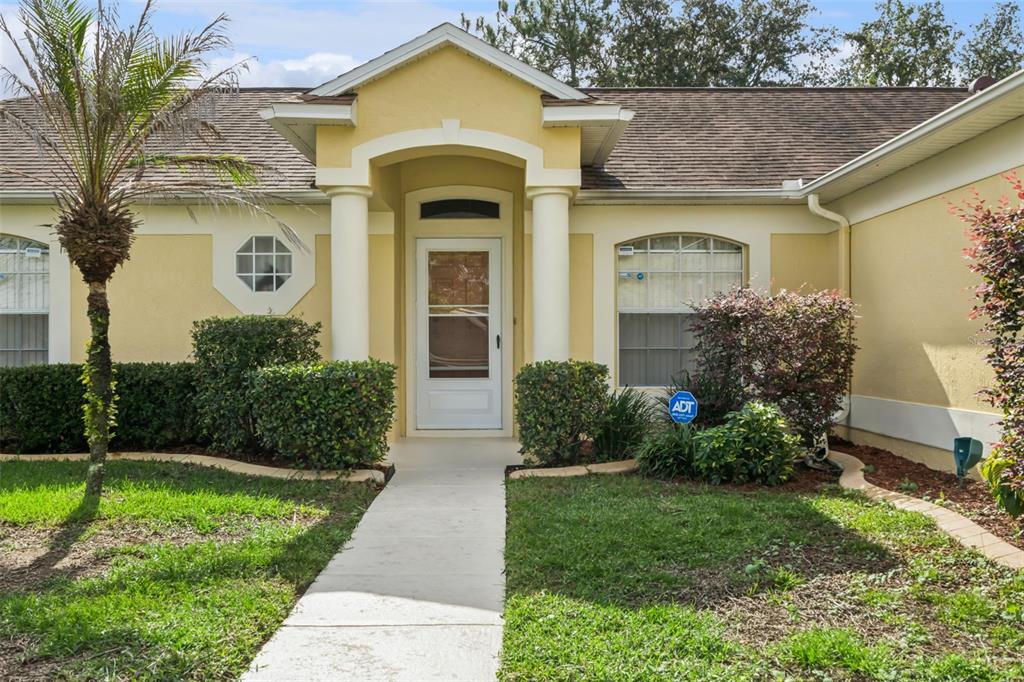
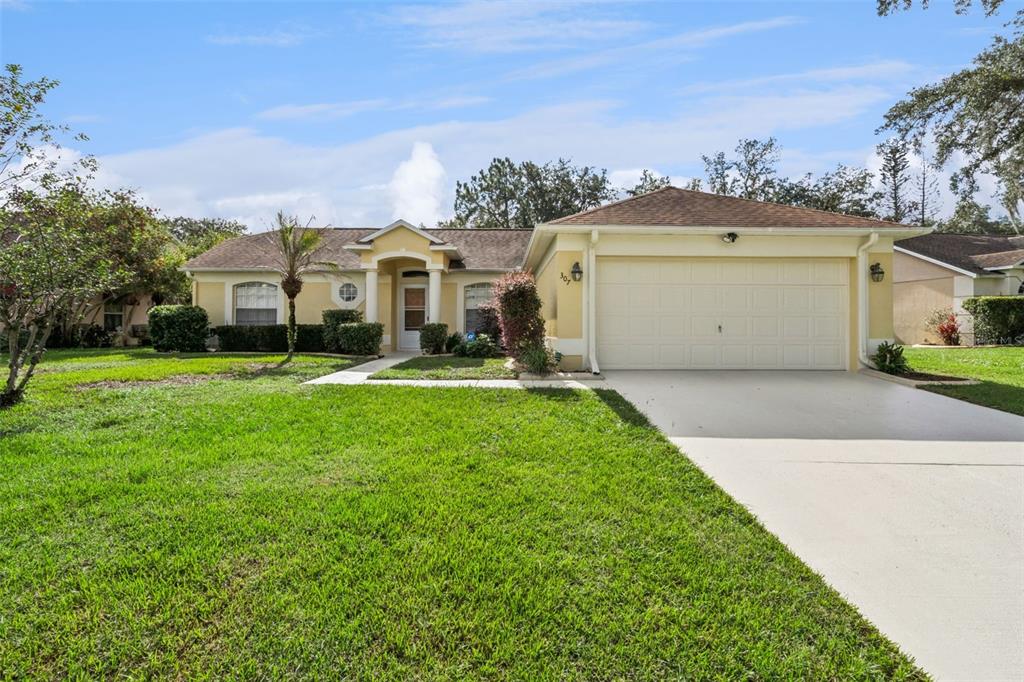
307 Hanging Moss RoadDavenport, FL, 33837
- 3 beds
- 2 baths
- 1,365 sqft
Central Florida buyer guide
Compare Florida homes for sale with our team. Explore our new build vs resale and review the actual property's setting and ownership details.
The live comparison uses the saved mapped area or selected communities. Confirm the actual home's rights, condition and ownership arrangements; the grid is not a membership, management or rental-eligibility certification.
Compare Florida homes for sale across new-build and resale routes with our team. We help you weigh the complete property cost, timing and ownership responsibilities.
When comparing a new build vs resale home in Florida, we suggest starting with your plans, not the home's age. If you are relocating to Central Florida, consider when you need possession, what must be done before moving in and what ownership will cost month to month. If you are buying an Orlando-area second home, weigh personal use first; if rental use is part of the plan, verify eligibility for the specific property. A completed new home is a different timing proposition from one yet to be built. This guide gives you a method for comparing properties across the area, not just within one community.
Enter property-specific amounts. Separate one-time cash needs from ongoing expenses; a deposit credited at closing is not a second purchase cost.
| Aspect | New-build input | Resale input | Document or quote to obtain |
|---|---|---|---|
| Purchase price, one-time | Agreed price: ____ | Agreed price: ____ | Contract and written inclusions |
| Property work, one-time | Lot premium, upgrades, excluded work: ____ | Expected repairs or replacements: ____ | Specification, selections and work quotes |
| Cash needs, one-time | Deposit: ____; cash due at closing: ____ | Deposit: ____; cash due at closing: ____ | Contract and closing estimate; count deposit only once |
| Financing, one-time | Charges and conditional credits: ____ | Charges and conditional credits: ____ | Comparable written Loan Estimates |
| Furnishings and appliances, one-time | Missing items and setup: ____ | Missing items and setup: ____ | Inventory of inclusions and supplier quotes |
| Insurance, ongoing | Premium and coverage: ____ | Premium and coverage: ____ | Property-specific insurance quotes |
| Property tax, ongoing | Your post-purchase estimate: ____ | Your post-purchase estimate: ____ | County property appraiser information |
| HOA and CDD, ongoing | HOA: ____; any CDD: ____ | HOA: ____; any CDD: ____ | Association and district documents |
| Routine ownership, ongoing | Utilities and maintenance: ____ | Utilities and maintenance: ____ | Service quotes and property records |
| Rental operations, if applicable | If rental use is eligible, expenses: ____ | If eligible, documented expenses: ____ | Eligibility checks and expense records or quotes |
A completed new home, a home still under construction and an occupied resale present different scheduling questions. For a new build, read the delivery provisions and ask when an upfront builder deposit is returnable, a question highlighted in federal home-search guidance. For a resale, compare the contracted possession date, inspection provisions and any repairs needed before you can move in. Neither a proposed construction completion date nor an existing home's availability alone tells you when it will be ready for your plans.
A builder's financing credit is only one part of an offer. Request comparable written Loan Estimates, then examine the rate, financing charges, cash due at closing and conditions attached to each credit. If construction could shift the closing date, ask how long the rate lock lasts and what an extension would cost. Buyers planning a second home or possible rental should discuss their intended use with lenders rather than assume the same terms apply to both. Our vacation-home mortgage guide explains that distinction in more detail.
Use your intended occupancy and actual contract terms to assess each property, not a presumed advantage of either route.
| Aspect | New build: what to check | Resale: what to check |
|---|---|---|
| Relocator: moving date | Check delivery terms and whether construction is complete. | Check possession terms and work needed before occupancy. |
| Upfront cash | Review deposit amount, refund terms and closing cash. | Review deposit, inspection provisions and closing cash. |
| Financing | Compare Loan Estimates and any conditional builder credit. | Compare Loan Estimates and any available credit terms. |
| Condition and coverage | Inspect independently; read the applicable warranty. | Inspect systems; request repairs and warranty records. |
| Ready for everyday or second-home use | Price upgrades, excluded work and missing furnishings. | Price repairs, replacements and missing furnishings. |
| Recurring costs | Check taxes, insurance, HOA and any CDD assessments. | Check your post-purchase taxes, insurance, HOA and any CDD. |
| Potential rental owner | Verify parcel-specific rental eligibility before planning to rent. | Verify eligibility; test any claimed rental history against records. |
Ask for the parcel's HOA documents and any CDD assessment details: association charges and district assessments are not interchangeable. Florida's 2026 CDD statute addresses disclosure for initial sales within a district and notes that district taxes or assessments may be imposed in addition to other taxes and set annually. Estimate your own post-purchase property tax rather than carrying over the seller's bill; Florida's Department of Revenue explains that the seller's exemptions and assessment limits may not transfer. Homestead eligibility concerns a qualifying permanent residence, not an assumed second home. Obtain property-specific insurance quotes and consider flood coverage separately, since standard homeowners insurance does not cover flood damage.
Arrange an independent inspection for either route. An appraisal addresses value for lending purposes; it does not replace a condition inspection. Under the 2026 Florida builder-warranty statute, qualifying previously unoccupied single-family homes, duplexes, triplexes and quadruplexes have limited mandatory coverage for specified construction defects that materially violate the Florida Building Code. It runs for one year from initial conveyance or occupancy, whichever occurs first, not for every defect or appliance. Read any express warranty and its transfer terms. For resale, inspect the systems and request repair and warranty records rather than assuming equivalent coverage.
Top Villas Intelligence
Create a free account to see projected rental revenue, ownership costs and operating yield on every eligible listing.
A condo calls for a different document review from a single-family home. Florida's 2026 condominium resale-disclosure statute identifies governing documents, financial statements and budgets among purchaser materials, plus applicable milestone-inspection summaries and structural integrity reserve studies. Review the particular association's reports, budget and potential assessments, and ask which requirements apply to the building. Do not assume a single-family builder warranty or mandatory-HOA disclosure describes a condo's coverage or obligations.
Neither new construction nor a resale's past rental operation gives you permission to rent. Within Orlando city limits, the city's home-sharing registration does not authorize an individual homeowner to rent an entire home for a short stay; whole-property commercial dwelling use depends on appropriate zoning and a business tax receipt. For Kissimmee, Davenport-area or unincorporated Osceola County properties, identify the actual jurisdiction and check its rules separately, along with any state licensing, association and insurance requirements. A resale's receipts and expenses can document past activity, not establish future income.
If rental use matters to your purchase, complete these checks before treating a property's history or marketing as evidence of eligibility.
Confirm the property's municipality and county from its address and parcel details. A Kissimmee or Davenport-area address does not establish that Orlando city rules apply.
Check the applicable zoning, permissions and licensing requirements for your intended use. Read the association documents for separate restrictions.
Ask for insurance terms and discuss the intended occupancy with your lender. Do not assume terms for a personal-use home also fit a planned rental.
For a resale with a claimed rental history, request address-specific receipts, booked periods, operating expenses and applicable permissions. Test what the records show without treating past results as a forecast.
A property marketed as being in the Orlando area may sit outside Orlando city limits. Confirm its municipality, county and association before applying rental rules or comparing ownership costs. For a full-time move, consider how the location fits your daily routine; for a second home, weigh how you expect to use it personally. You can explore Orlando and Winter Garden as starting points, then check the details of each property rather than assuming the two locations have identical rules or costs.
Gaby Sadler
Property Specialist, Serhant
Considering Florida homes for sale? I'll help you apply this new build vs resale to your shortlist, compare the actual property and ownership details, and plan your next steps.
Use the decision matrix to narrow your priorities, then fill in the worksheet for the actual homes you are considering. A delivery date, a builder credit or a past rental record means little without the contract terms and property-specific costs behind it. We can help you compare how a home fits your move, second-home plans or intended ownership use as you explore properties for sale.
Explore Mount Dora new construction, Ocoee new construction and Cape Coral new construction to apply the comparison to different locations. Each guide keeps builder offerings and completed resales in context, so you can assess the specific homesite, specification and timing.
 Orlando homes for sale: property buying guides
 Florida homes for sale: 1031 exchange guide
 Florida homes for sale: condo document guide