
Skip to content
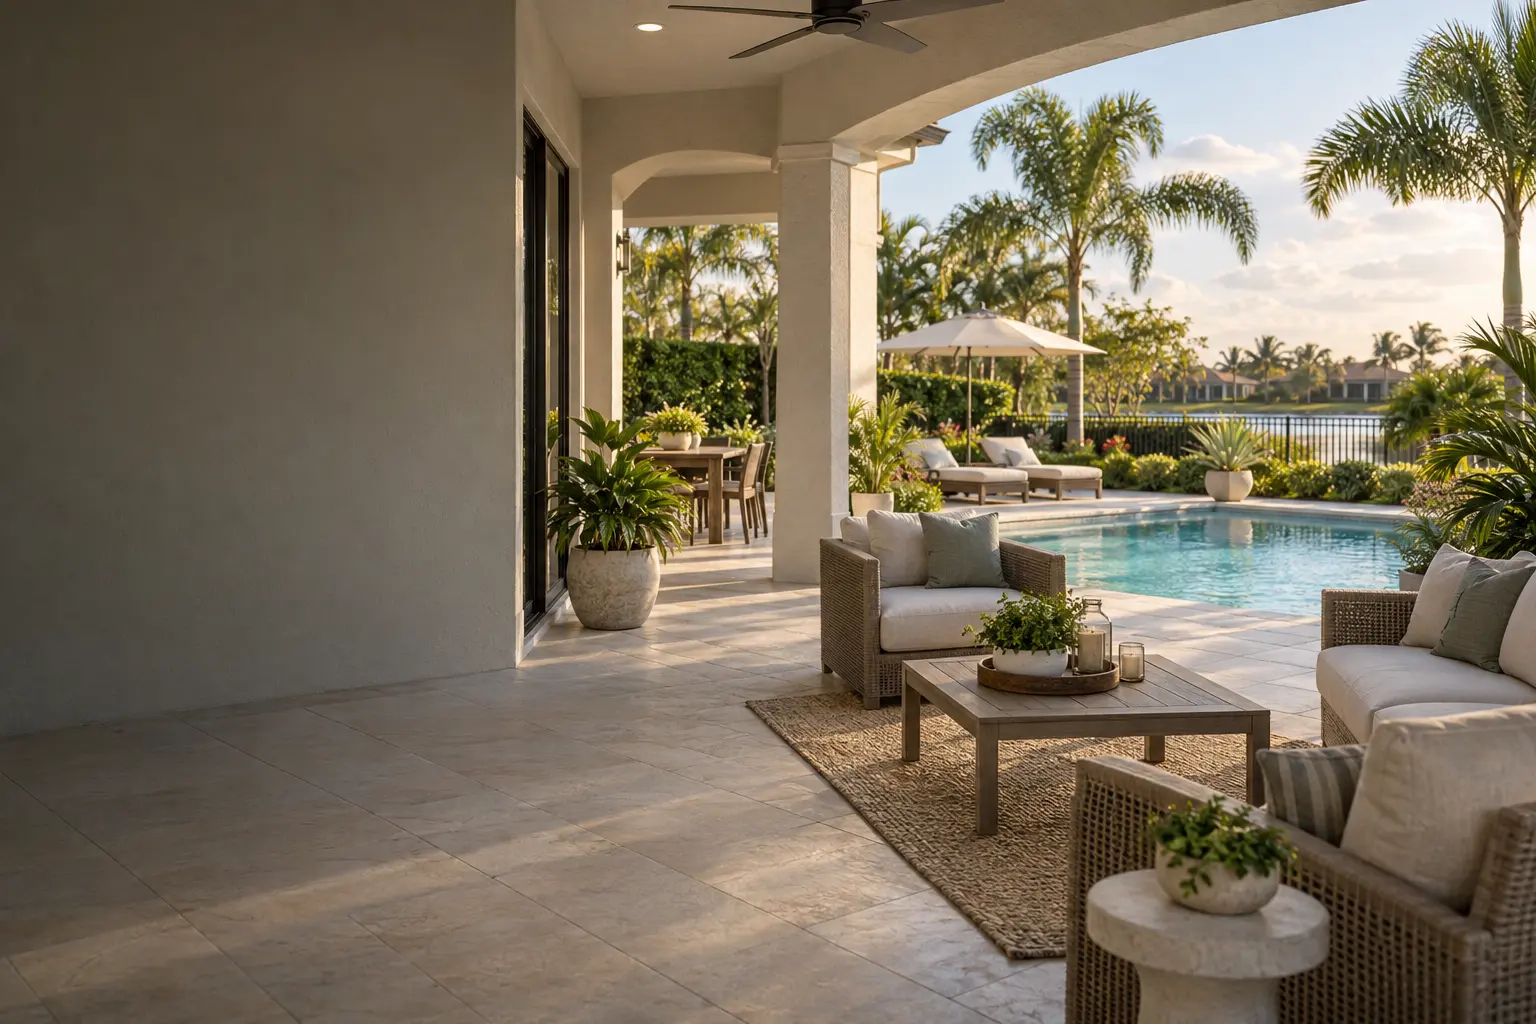
Illustrative Florida home's covered terrace overlooking a turquoise pool, landscaped garden and palms in warm daylight.

A practical guide for UK buyers

Florida homes for sale: buying a Florida home from the UK, offer to completion

We explain the key decisions from offer to handover, including remote closing. Your signed contract controls obligations and deadlines.

Agree representation before you tour

Buying a Florida home from the UK, from offer to completion, starts with understanding representation. As you explore Florida homes for sale, applicable multiple listing service (MLS) participation rules require a participating representative working with you to obtain a written buyer agreement before an in-person or live virtual tour. This is not a blanket Florida statute covering every interaction; attending an open house independently is different. Review services, duration, exclusivity, termination and compensation before signing. Compensation is negotiable, not fixed by law. Seller contributions are also negotiable, so understand what you may owe if another party does not cover the agreed amount.

Your pre-offer readiness checklist

Confirm UK documentation requirements with your lender and closing agent. Requirements depend on your transaction.

  • Confirm your cash evidence

    Ask what evidence of available cash is acceptable for your offer. Proof of funds is distinct from mortgage approval.

  • Establish mortgage readiness

    Pre-approval is tentative, not final underwriting approval. Explore our [mortgage guide](/guides/vacation-home-mortgage-options).

  • Prepare your documents securely

    Prepare identification, financial statements, income evidence and liabilities. Share sensitive documents through an agreed secure channel.

Who does what during your purchase?

AspectRoleWhat to confirm
RepresentationBuyer representativeNegotiation and transaction coordination within the agreed scope of services.
Legal reviewIndependent Florida attorneyIndependent counsel on your contract, rights, ownership arrangements and identified concerns.
FinancingLenderUnderwriting requirements, approval conditions and readiness to fund.
ConditionInspectorPhysical-condition assessment, inspection scope and any recommended specialist checks.
SettlementClosing/title agentTitle and settlement functions. This role is not automatically your independent legal adviser.

From negotiated offer to completion

Your executed contract controls obligations, deposit amounts, deadlines, notice methods and calendar rules.

  1. Settle the offer terms

    Confirm parties and signing authority, property, included contents, price, deposit, contingencies, cost allocation, closing date and possession before signing.

  2. Complete contractual acceptance

    Under commonly used Florida residential forms, the effective date follows the final signature or initials and delivery of acceptance. Check your contract's requirements.

  3. Deliver the escrow deposit

    Send the agreed deposit to the named escrow holder by the contractual deadline, using independently verified payment instructions. Obtain a receipt.

  4. Run checks in parallel

    Arrange inspections, title review, financing and insurance together. These tasks overlap rather than waiting for one another.

  5. Make the proceed-or-withdraw decisions

    Resolve outstanding conditions or exercise available contractual rights with the required notices before their deadlines.

  6. Prepare for completion

    Review settlement documents, arrange the final walk-through and coordinate signing, funding and possession with the closing team.

Inspection, appraisal and financing: different decision points

AspectCheckWhat it establishesYour decision point
ConditionPhysical inspectionAssesses condition, not lending value. Findings can inform your decision.Proceed, seek agreement on repairs or price, or use an available exit. The seller need not agree to changes.
Inspection protectionAS IS inspection rightsAS IS need not mean no inspection. Cancellation rights depend on the actual form.Give timely written notice as the clause requires. Do not assume all contracts offer the same exit.
ValueAppraisalEstimates value for lending purposes; it does not replace inspection.A low value does not automatically lower the price or allow withdrawal. Check financing and appraisal clauses.
Loan protectionFinancing approvalEstablishes the lender's decision and any remaining conditions.Pursue financing diligently and give required notices. Loan refusal alone does not entitle you to a deposit refund.

Review title, liens and the survey before deadlines pass

Have ownership, liens and the title commitment's requirements and exceptions reviewed while contractual objection rights remain available. An owner's title policy protects your covered interest; a lender's policy protects the lender, and neither offers unconditional coverage. A boundary survey locates boundaries and improvements and can identify encroachments. It is not a building-condition survey or a substitute for inspection. Condominiums and new construction require separate document and contract review, particularly where a builder uses its own agreement. Our condominium-document guide and new-build versus resale guide explain the additional considerations.
Check insurance while you still have choices

Obtain property-specific insurance information early enough to assess availability, terms and lender requirements before relevant contractual deadlines. Ordinary homeowners policies generally exclude flood damage, so separate flood coverage may be necessary and some mortgages require it. Confirm your intended second-home use and any relevant wind-mitigation evidence with the insurer. Do not assume a home used periodically will have the same underwriting terms as a continuously occupied primary residence.

Plan your remote signing and time zones early

Florida has Eastern and Central time areas, and UK and US clock-change dates differ. Confirm the property's local time zone.

  • Approve the signing route

    Obtain lender and closing-team approval. Generic electronic signatures or UK notarisation may not satisfy closing requirements.

  • Test identity checks

    Test identification and authentication early. Florida permits compliant online notarisation, but eligibility depends on successful checks.

  • Map document requirements

    Confirm which documents need notarisation, witnesses or originals, plus delivery deadlines and courier arrangements.

  • Check an overseas alternative

    An in-person US consular notarial appointment may be an option where accepted and available. This service is not virtual.

  • Coordinate both time zones

    Record contract deadlines, bank cutoffs and appointments separately in local and UK time. Arrange a local final walk-through representative.

Your final checks before completion and handover

  1. Review settlement and loan documents

    For mortgages covered by federal disclosure rules, receive the Closing Disclosure at least three business days before consummation. Compare it with the Loan Estimate, including terms, fees, credits and cash to close. Not every correction restarts the waiting period.

  2. Conduct the final walk-through

    You or your representative should check included contents, required maintenance and agreed obligations within the contractual timing. This is not a replacement for the earlier inspection.

  3. Confirm documents and funding

    Confirm the closing team has the required executed documents and collected funds. Signing alone does not establish completion.

  4. Confirm completion and handover

    Establish who confirms completion and authorises release of keys and access devices. Follow the possession terms, including any separate occupancy agreement.

Keep one organised purchase file

Your final file is transaction-specific. Identification and financial records belong in agreed secure channels.

  • Agreements and money

    Keep the buyer agreement, accepted contract, riders, amendments and deposit receipt together.

  • Deadlines and notices

    Retain your deadline diary, required notices and evidence of their delivery.

  • Due diligence and approvals

    Save inspection reports, title commitment, applicable survey, financing correspondence and insurance evidence.

  • Completion records

    Keep final settlement documents and signed closing papers for your ownership records.

Florida buying terms for UK buyers

Closing or settlement
Broadly comparable to completion, when required documents and funds complete the transaction; possession follows the agreed terms.
Earnest money
The contractual purchase deposit, not necessarily your entire down payment.
Escrow
Holding money or documents under agreed conditions, not equivalent to exchange of contracts in England and Wales.
Appraisal
A valuation used for lending purposes, distinct from a physical-condition inspection.
Boundary survey
A survey of boundaries and improvements, not the equivalent of a UK building survey.
Title commitment
Requirements and exceptions for proposed title insurance, not the issued policy.
Contingency
A contractual condition with specific requirements and deadlines, not an unconditional withdrawal right.

Your offer-to-completion questions answered

Gaby Sadler, Property Specialist

Gaby Sadler

Property Specialist, Serhant

Talk to Gaby about buying in Florida from the UK

I can arrange viewings, answer your questions and prepare a personalized rental projection for any home you're considering.

Take your next step towards owning in Florida

Tell us about your plans for a Florida second home and how you expect to use it. We can help you explore properties and understand the buying journey. For the wider picture, read our UK buyer guide, then start comparing homes that fit your priorities.

Browse Florida homes for sale