
Skip to content
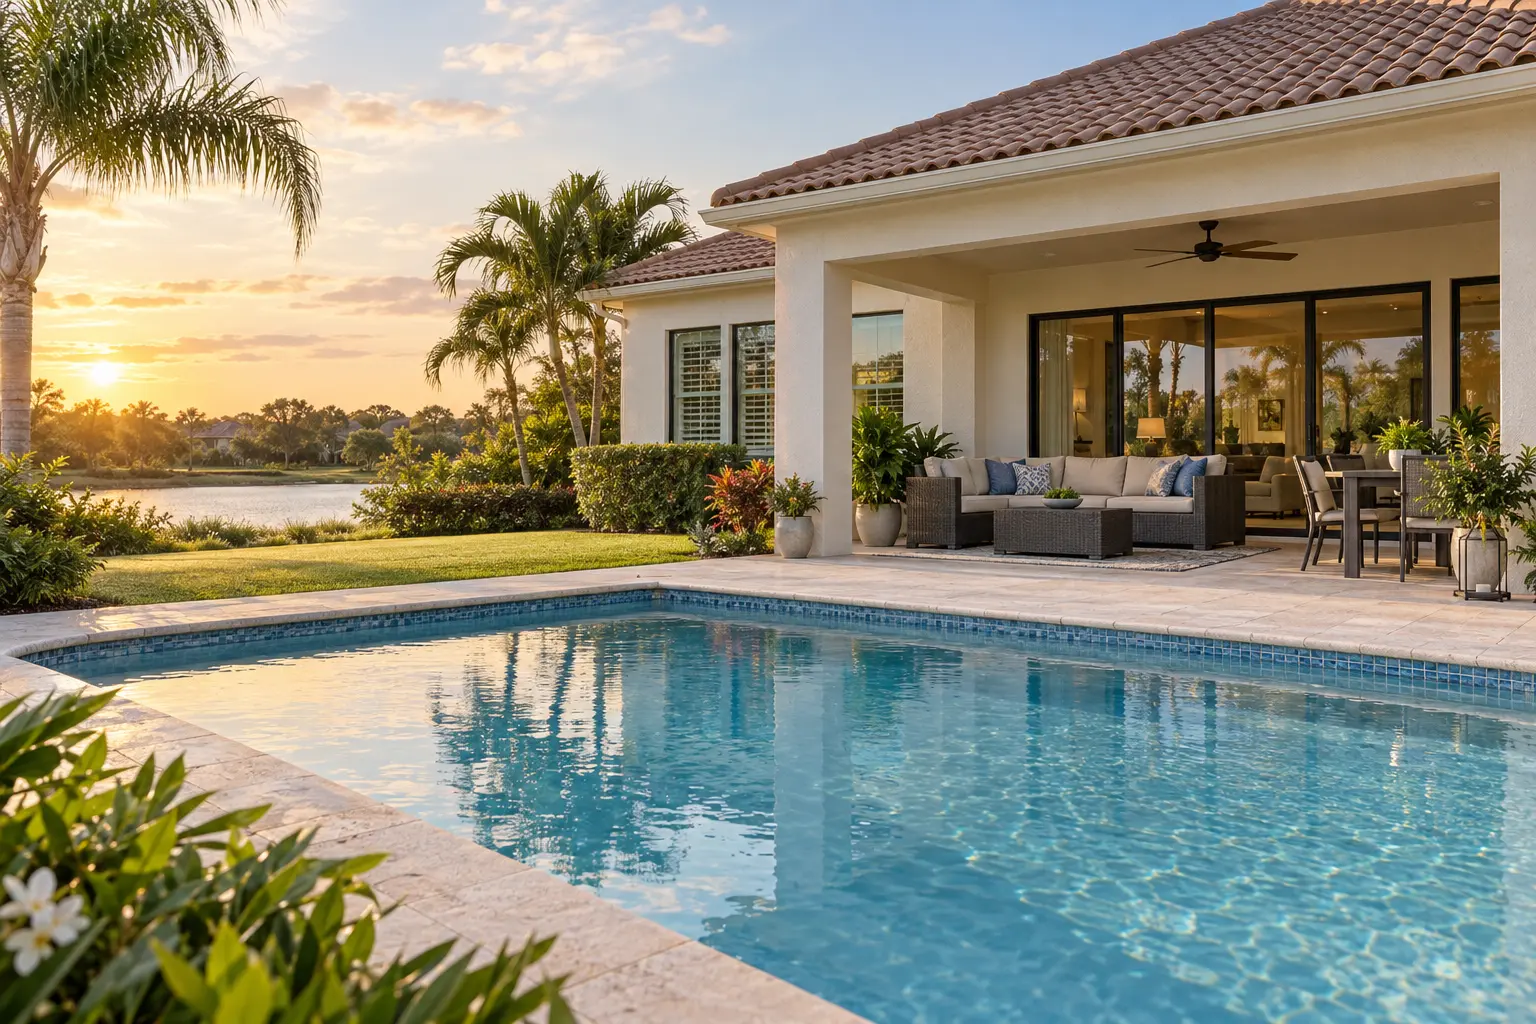
Illustrative Florida detached home with a private swimming pool, covered terrace and palm landscaping in warm afternoon light.

UK buyer guide

Florida homes for sale: a holiday-home ownership budget for UK buyers

Plan upfront cash, annual bills and sterling exposure for your Florida second home, with worked examples that do not depend on rental income.

Start with the money you need, not assumed rental income

Before comparing Florida homes for sale, build a holiday-home ownership budget that separates acquisition cash, recurring bills, debt payments and retained reserves. We focus here on UK buyers' funding, sterling exposure and payment timing, rather than rental income. Use our UK purchase guide for the broader process and our Orlando villa ownership-cost guide for local costs. This is general education: replace every illustrative allowance with property-specific quotes and take individual tax, legal and borrowing questions to qualified professionals.

Build your budget from documents and quotes

Use dated documents, not a universal closing-cost percentage.

  1. Collect the acquisition evidence

    Request an itemised settlement estimate, inspection and survey quotes, financing terms, association budgets and an estoppel certificate showing current charges. Identify deposits already paid: they form part of purchase funding, not an extra cost. Financing documents vary by loan.

  2. Price the home you intend to own

    Obtain written insurance, service, furnishing, club and utility quotes. Record dates, expiry, included services and prepaid periods. For insurance, disclose intended use and periods away; confirm dwelling and contents limits, wind and flood coverage, exclusions and deductibles.

  3. Map when the money is needed

    Schedule each payment and retained reserve by date and currency. Distinguish the final cash to close from total acquisition and setup funding. Record any prepaid ownership costs so they appear in the cash timetable without being counted twice.

Four checks that prevent an understated budget

Replace allowances with evidence for the address, ownership structure and intended use.

  • Request a buyer-specific county tax estimate

    Ordinary ownership changes trigger reassessment on 1 January after purchase. The seller's bill may understate yours; do not assume holiday-home homestead relief

  • Separate HOA and CDD charges

    A CDD is a public district, not the HOA. Count the complete tax bill or its components, never both. Reconcile included services against budgets and tax records.

  • Check club terms independently

    Verify joining fees, annual dues, minimum spending and access rights in membership documents. An association estoppel cannot rule out every future assessment.

  • Separate premiums from cash needed for a loss

    A hypothetical 2% hurricane deductible on $900,000 dwelling cover is $18,000, not 2% of the purchase price. This is arithmetic, not an available policy offer.

Illustrative annual budget: $83,900 before mortgage payments

Hypothetical $1,200,000 detached second home with pool, HOA, CDD and separate club. No rent or mortgage. Assumptions, not quotes, averages or recommended sums.

AspectCost groupHypothetical annual USD allocationAccounting note
Property taxValue-based property taxes$18,000Excludes CDD; replace with a buyer-specific estimate.
DistrictCDD assessment$3,000Separated from the tax bill; check debt and operating components.
AssociationHOA dues$9,000Private services below assumed excluded; check master and subsidiary associations.
MembershipSeparate club dues$6,000Joining charge appears in the upfront budget.
Home coverageHomeowners' insurance$9,000Assumes wind coverage; confirm exclusions and association-policy overlap.
Flood coverageSeparate flood insurance$1,500Most homeowners' policies exclude flooding.
Household billsUtilities$9,000: electricity $6,000; water/sewer/refuse $1,800; internet $1,200Assumes these services are not charged elsewhere.
Outdoor upkeepPrivate-home services$5,400: pool $2,400; lawn $2,400; pest $600Check HOA inclusions before adding contracts.
Care while awayHome checks and routine repairs$3,000: checks $1,800; repairs/servicing $1,200Separate routine work from future replacements.
Future workReplacement-reserve contribution$12,000Retained cash, not current spending or a recommended minimum.
Personal visitsOwner travel$8,000USD-equivalent allowance only; actual GBP bills stay in GBP.
TotalAnnual funding allocation$83,900$71,900 modelled spending plus $12,000 retained reserves.

Illustrative upfront cash beyond the purchase price

Beyond the $1,200,000 cash purchase price. These are placeholders, not statutory allocation rules, property quotes or reserve recommendations.

AspectAdditional funding itemHypothetical USD amount
TransactionSettlement, title, legal, recording and transaction charges$18,000
Due diligenceInspections and survey$2,500
AssociationAssociation transfer and initial contributions$3,000
MembershipSeparate club joining charge$10,000
FurnishingFurniture, equipment and installation, including assumed taxes and delivery$75,000
ConnectionsUtility deposits and setup$2,500
Money transferTransfer and banking charges, USD-equivalent allowance$2,000
Cash bufferOpening contingency cash retained$30,000
PrepaymentsFirst-year homeowners' and flood premiums prepaid$10,500
TotalAdditional upfront funding$153,500; with purchase: $1,353,500 across acquisition and setup, not necessarily the settlement wire.

Reconcile prepayments and retained cash

Acquisition plus one modelled ownership year is $1,200,000 + $153,500 + $83,900 − $10,500 prepaid insurance = $1,426,900, including retained reserves. The remaining ownership-year funding after prepayments is $73,400. The $30,000 opening contingency and $12,000 annual replacement contribution are separate here; record whether your own funds overlap. Base replacement provisions on inspection findings and component condition, not a universal percentage. Actual settlement adjustments and payment periods must replace this simplified timing, which is not an exact first-calendar-year forecast. A reserve is cash you retain, not necessarily money you spend that year.
Test your budget at two hypothetical sterling rates

Hypothetical rates, not quotes or forecasts. GBP required = USD obligation ÷ USD per £1, before separate fees. Sterling totals rounded to the nearest pound.

AspectFunding itemUSDGBP at £1 = $1.30GBP at £1 = $1.10
Acquisition extrasAdditional upfront$153,500£118,077£139,545
Ongoing ownershipAnnual allocation$83,900£64,538£76,273
Combined fundingAcquisition plus model year$1,426,900£1,097,615£1,297,182

Compare delivered dollars, not just the advertised fee

Moving from $1.30 to $1.10 per pound makes an unchanged dollar bill approximately 18.18% more expensive in sterling. Compare the total pounds needed to deliver the required net dollars by your deadline, including rate markups, fixed, variable and intermediary charges. “Zero fee” does not mean zero cost. Keep actual GBP obligations outside conversion and count the example's transfer allowance only once. Non-bank payment-provider balances lack Financial Services Compensation Scheme (FSCS) protection against provider failure. Authorised payment and electronic-money institutions use safeguarding instead; small payment institutions need not. Neither authorisation nor safeguarding ensures immediate recovery of funds.

Keep cash, sterling borrowing and dollar borrowing separate

Compare documented terms with a licensed lender; no route implies eligibility or a preferred borrowing strategy.

AspectFunding routeCurrency exposureWhat to confirm
Cash purchaseExisting GBP cashConversion exposure on purchase funds and later dollar bills.Net dollars delivered, transfer costs, timing and cash retained.
Sterling debtGBP borrowingPurchase funds convert to USD; debt service remains in GBP.Debt currency, upfront charges, repayment terms and security.
Dollar debtUSD borrowingA fixed dollar payment is not a fixed sterling payment.Debt currency, charges, terms, security and funding at weaker sterling.

Add mortgage principal and interest separately

For illustration only, a $600,000 fully amortising loan over 30 years at a fixed nominal annual 7% produces monthly principal and interest of approximately $3,991.81, or $47,901.78 annually using the unrounded payment. Adding this to ownership funding gives $131,801.78 annually: approximately £101,386 at $1.30 or £119,820 at $1.10. This is not an offer or eligibility indication; loan fees, any required mortgage insurance and lender reserves are excluded. Avoid adding escrowed taxes and insurance again. A financed upfront budget needs its own closing and escrow reconciliation, not simply the cash example minus the loan. Our vacation-home mortgage guide explains the wider financing considerations.

Your fill-in ownership funding worksheet

Repeat rows per cost; subtotal categories separately. Count overlaps once. Test normal and weaker sterling, keeping actual GBP obligations separate.

AspectCost category/itemEvidence and statusAmount and timingOverlap and funding
AcquisitionAcquisition item: ___Document/provider: ___; quote date/expiry: ___Currency/amount: ___; payment date: ___Deposit credited: ___; prepaid period: ___
OwnershipRecurring ownership item: ___Evidence: ___; mandatory/optional: ___; unconfirmed: ___Currency/amount: ___; frequency: ___; annual equivalent: ___Included elsewhere: ___; direct/escrow: ___; due date: ___
DebtDebt-service item: ___Loan terms/date: ___; outstanding confirmation: ___Currency/payment: ___; frequency/annual total: ___Escrow overlap: ___; payment dates: ___
ReservesReserve purpose: ___Inspection/component evidence: ___; review date: ___Currency/opening cash: ___; annual contribution: ___Separate or shared fund: ___; funding date: ___
TravelDiscretionary travel item: ___Quote/date/expiry: ___; optional plans: ___Currency/amount: ___; frequency/annual total: ___Already funded: ___; due date: ___; GBP kept separate: ___

UK buyer ownership-budget questions

Gaby Sadler, Property Specialist

Gaby Sadler

Property Specialist, Serhant

Build your Florida home ownership budget with Gaby

I can arrange viewings, answer your questions and prepare a personalized rental projection for any home you're considering.

Find a Florida home that fits your ownership plan

Use your quote-led budget to compare homes with a clearer view of upfront funding, annual commitments and sterling exposure. We can help you discuss property-specific ownership charges as you build your shortlist, keeping the home's suitability for your personal use alongside its purchase price.

Browse Florida homes for sale