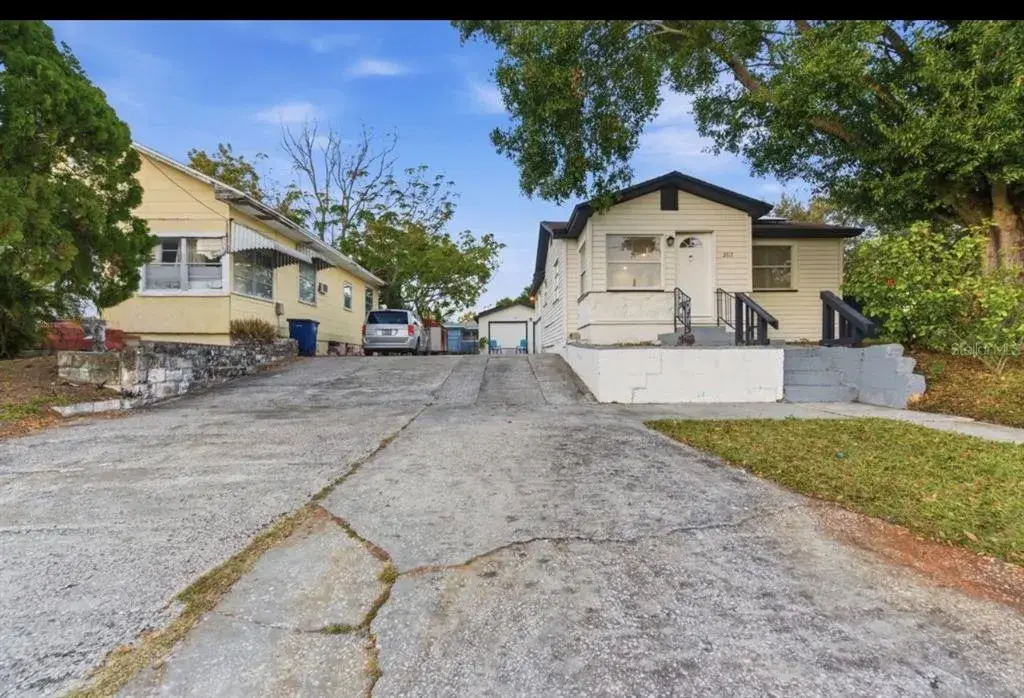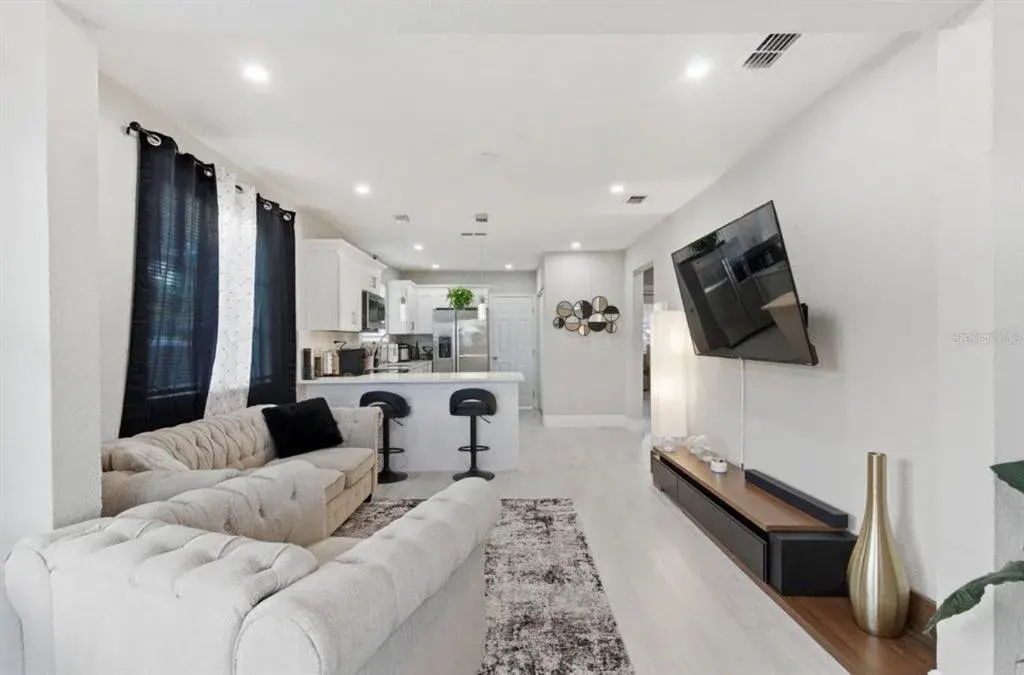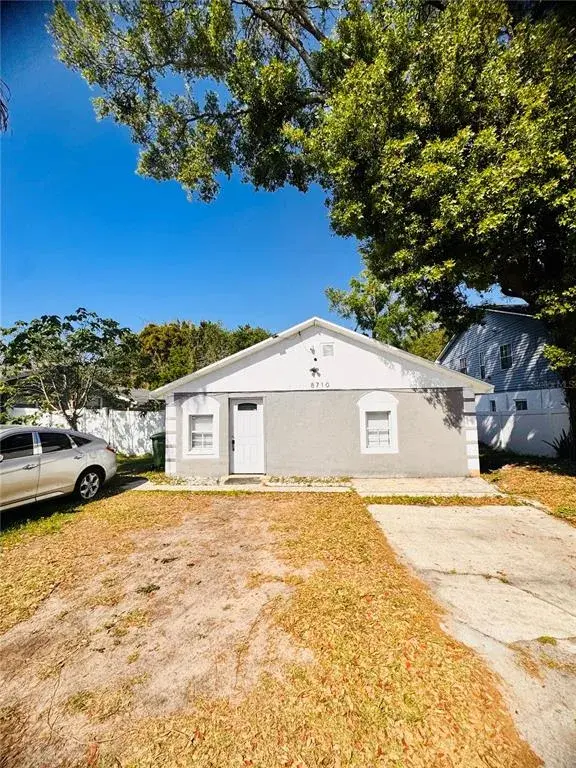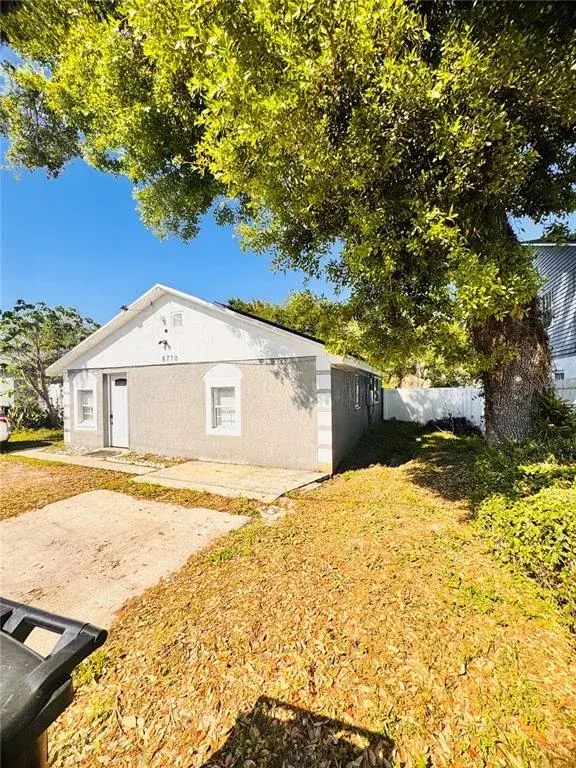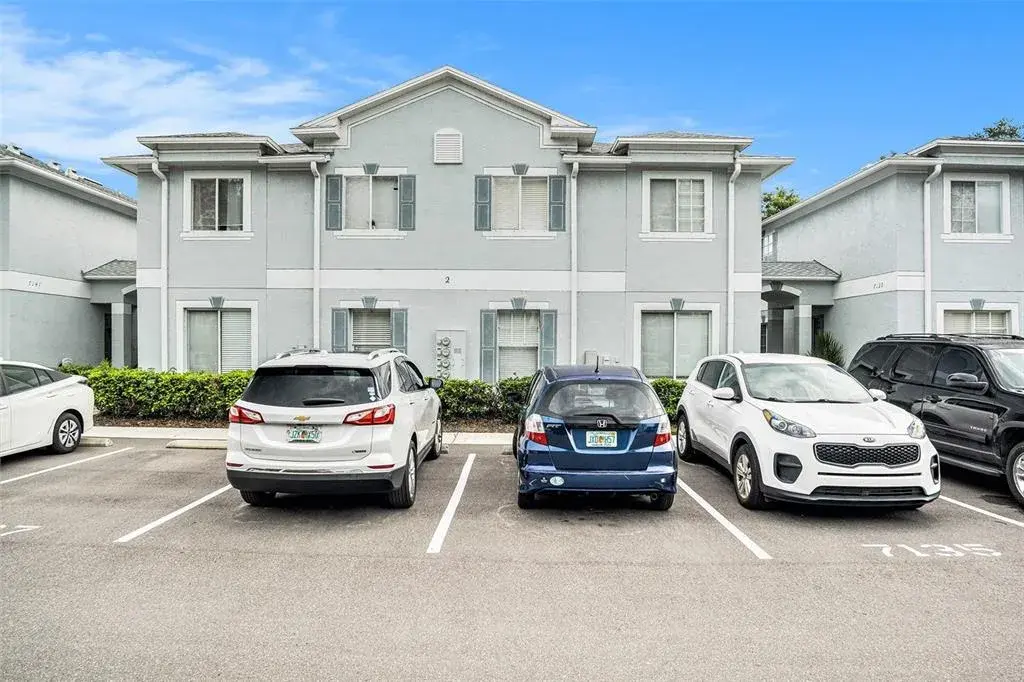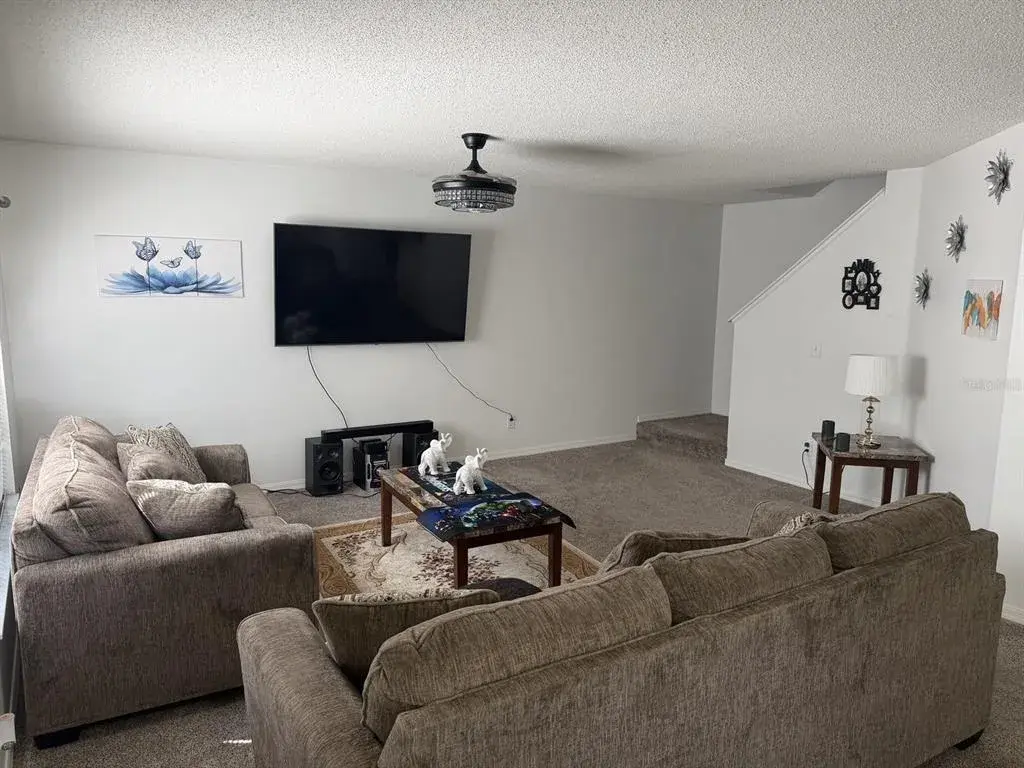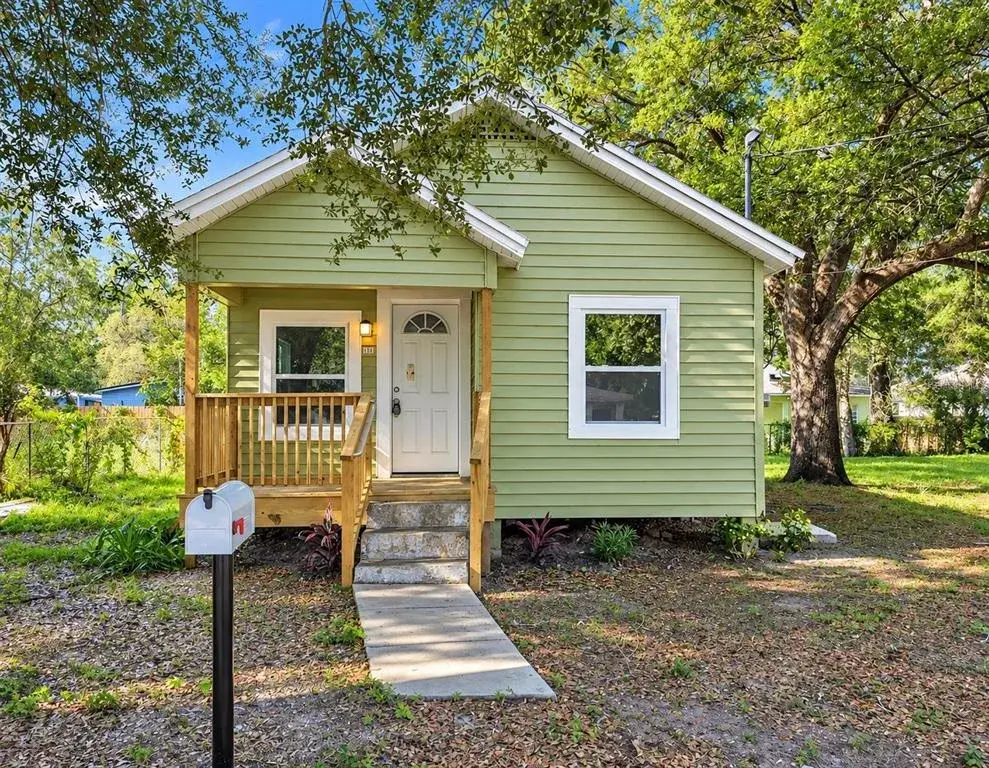
 212 days on market
$3,500,000Price increased by $500,000 on Nov 3, 2026
Short sale
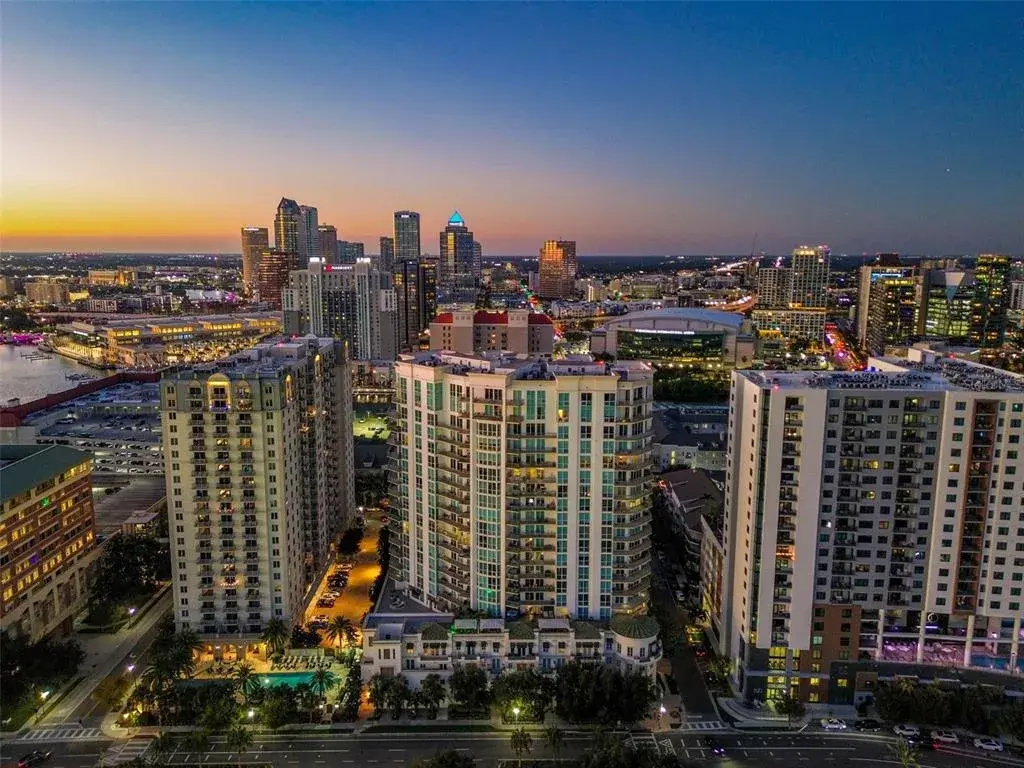
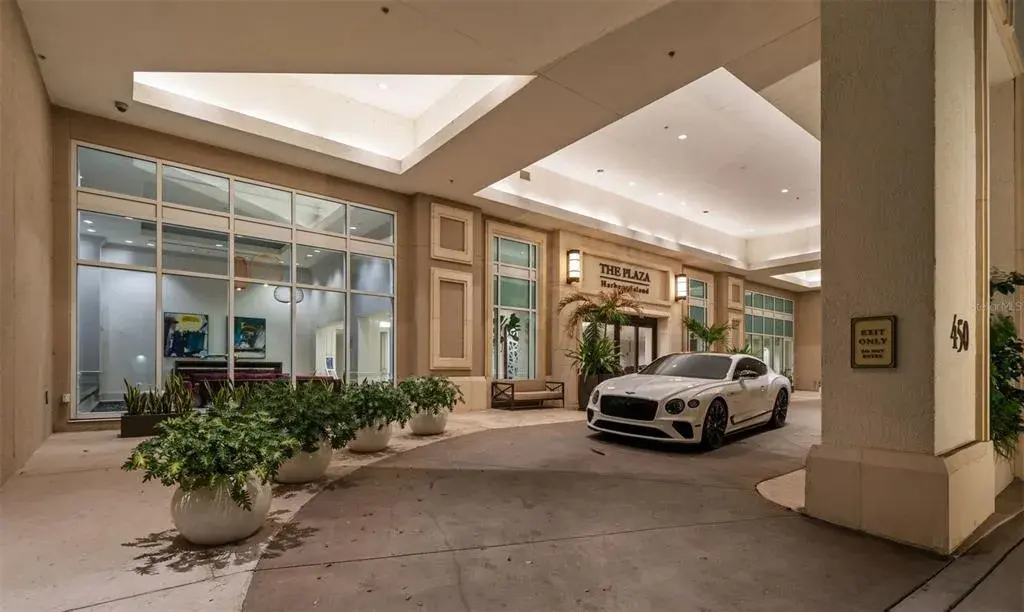
450 Knights Run Avenue Unit 2004Tampa, FL, 33602
- 3 beds
- 4 baths
- 3,980 sqft
Short-sale Real Estate
Compare current city-boundary listings and understand lender approval, timing and property-specific checks. See Tampa homes for sale marked as short sales.
Tampa homes for sale include marketed listings with a Short Sale source condition. This Tampa short-sale search retains that condition within the saved city boundary, separate from REO listings and auction records. We help compare the actual home, documented approval stage and ownership costs against your moving plans and tolerance for timing uncertainty.
Each price search keeps the same Tampa city boundary and category filter. Figures reflect current asking prices.
All property types within Tampa city limits. These asking-price figures describe the wider city market, not this page's filtered category.
Top Villas Intelligence
Review available property reports, ownership costs and nearby-sale comparisons. Report availability varies by home.
Among Tampa homes for sale, short sales involve a purchase price below the outstanding mortgage balance, with the lender's or servicer's agreement. “Short” describes that debt shortfall, not a quick transaction or a discount against market value. We help you distinguish the seller's acceptance of your offer from the separate approvals needed from the mortgage servicer and loan owner. If the property has additional mortgages, further servicer approvals may be necessary. For you as a buyer, the important starting point is the property's current approval stage and the conditions attached to your offer. The listing designation alone does not establish an approved price, the home's physical condition or a closing date.
This search selects the exact Short Sale listing category. Bank-owned homes, foreclosure auctions and ordinary listings are not substitute categories.
| Aspect | Listed short sales | Bank-owned / REO | Foreclosure auctions | Ordinary listings |
|---|---|---|---|---|
| Ownership or sale route | An owner sells for less than the outstanding mortgage balance, subject to mortgage-party agreement. | A financial institution has acquired the property, including through foreclosure or a deed in lieu. | A separate court-sale process conducted through Hillsborough County's Clerk. | A listed property sale that does not require approval to accept a mortgage shortfall. |
| Distinguishing requirement | Seller acceptance is separate from approval by the relevant servicer and loan owner. | The institution is the owner, rather than a mortgage party approving an owner's short sale. | The court-sale route has its own bidder, deposit and payment requirements. | No shortfall approval is needed, although the purchase may have other contract conditions. |
| What not to assume | Do not assume the asking price is approved or below market value. | Do not treat bank ownership as the same category as a listed short sale. | Do not apply auction procedures to the short-sale listings shown here. | Do not assume the absence of short-sale review removes financing or inspection conditions. |
| Selected by this page's category filter | Yes | No | No | No |
Keep the seller's short-sale approval, your financing and your inspection conditions separate as you assess each property.
Ask what has already been submitted or approved and which mortgage parties still need to respond. Establish whether additional mortgages require separate approvals. Treat the Short Sale label as a starting point for questions, not confirmation that the proposed price or transaction terms have been accepted.
Prepare financing preapproval or evidence of funds appropriate to your offer. If you plan to borrow, discuss the property and any known repairs with a licensed lender. Your ability to obtain a loan is a separate question from whether the seller's mortgage parties will approve the short sale.
Have the appropriate professional explain the actual contract's approval conditions, deposit provisions, cancellation terms and deadlines before you commit. Ask specifically how inspection and financing deadlines interact with lender review. Do not assume your deposit is automatically refundable or that inspection periods begin only after short-sale approval.
Arrange an independent inspection within the agreed terms and assess what the findings mean for your plans and financing. A short-sale designation does not establish physical distress or mean repairs will be funded. Review repair questions under your contract rather than assuming the seller will address every issue.
The seller's lender may approve, counter or decline the offer. Review any response and revised terms with the appropriate professionals before proceeding. Revisit your budget, contract deadlines and moving plans if terms change, and confirm the status of your own financing and inspection conditions rather than treating lender approval as the final step.
A short sale can be difficult to plan around when your moving date is fixed. Lender review, approvals involving multiple mortgages and changes to negotiated terms can all affect progress, so assess your flexibility before committing to a particular home. Buying a primary residence or a second home does not, by itself, establish a faster approval route. If you need to coordinate a move closely, we can help you compare ordinary listings through our broader Tampa homes guide alongside short-sale options. If your schedule is more flexible, keep reviewing the property's approval stage and contract deadlines as the transaction develops. Flexibility gives you room to consider uncertainty, but it does not control the lender's decision.
Make these checks address-specific. The City's Natural Hazards Map provides flood and evacuation information, while property records help frame inspection needs
Confirm the municipal location
A Tampa mailing address may fall outside city limits. Check the property's address against the municipal boundary rather than relying on its postal label.
Review permits and property records
Use Tampa's Citizen Access records to check construction permits, planning records and code-enforcement complaints tied to the property's address.
Assess the home's actual condition
Get an independent physical inspection. Records do not replace it, and the Short Sale label establishes neither physical distress nor funded repairs.
Separate flood risk from evacuation zones
Check flood and evacuation zones separately for the property. A home outside an evacuation zone can still face significant flood risk.
102 properties sold within half a mile in the last 12 months · median $602,500
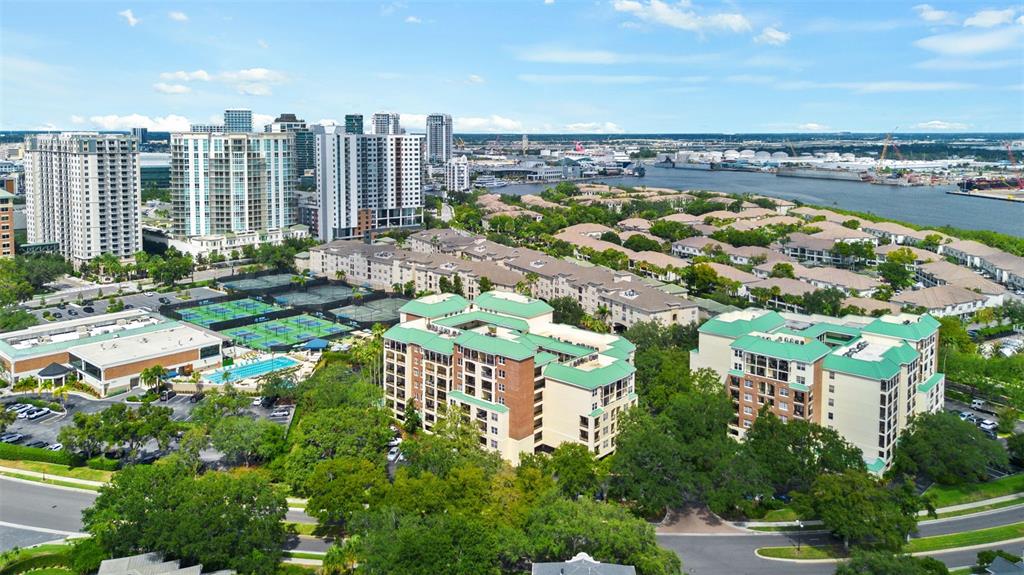
2 bed · 3 bath · 1,448 sqft
$635,000
Sold Nov 9, 2026
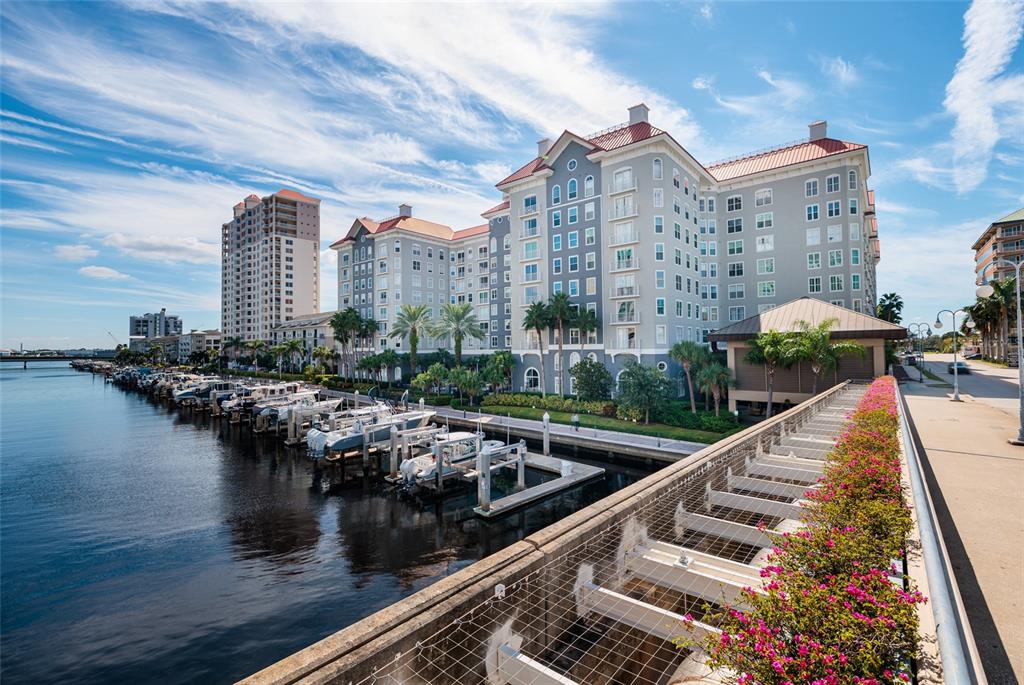
2 bed · 2 bath · 1,180 sqft
$555,000
Sold Oct 30, 2026
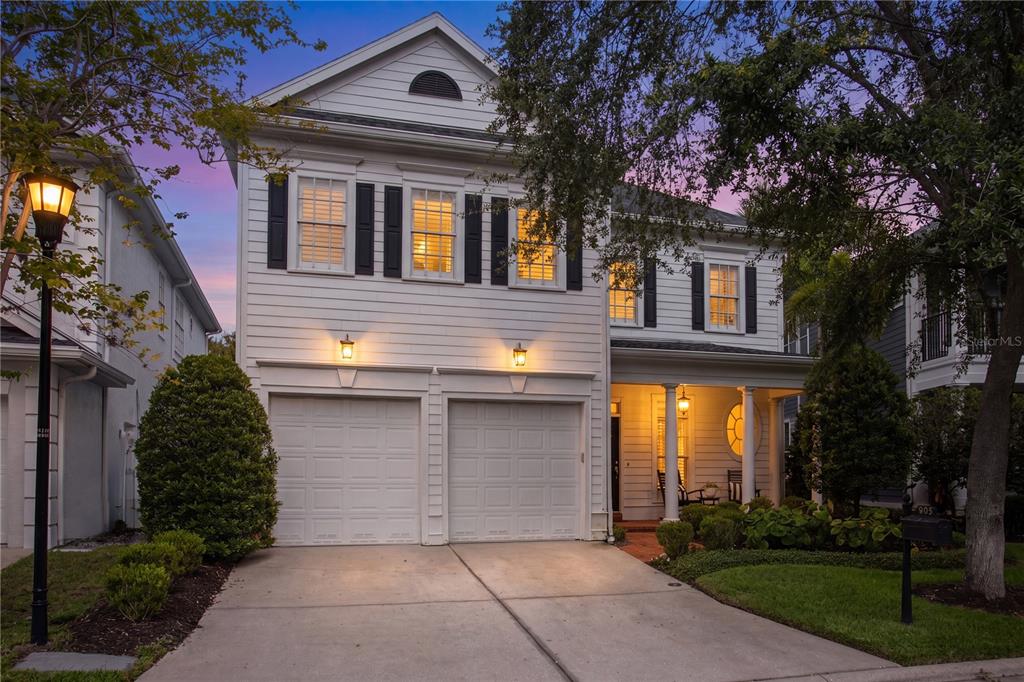
4 bed · 4 bath · 3,447 sqft
$1,995,000
Sold Oct 26, 2026
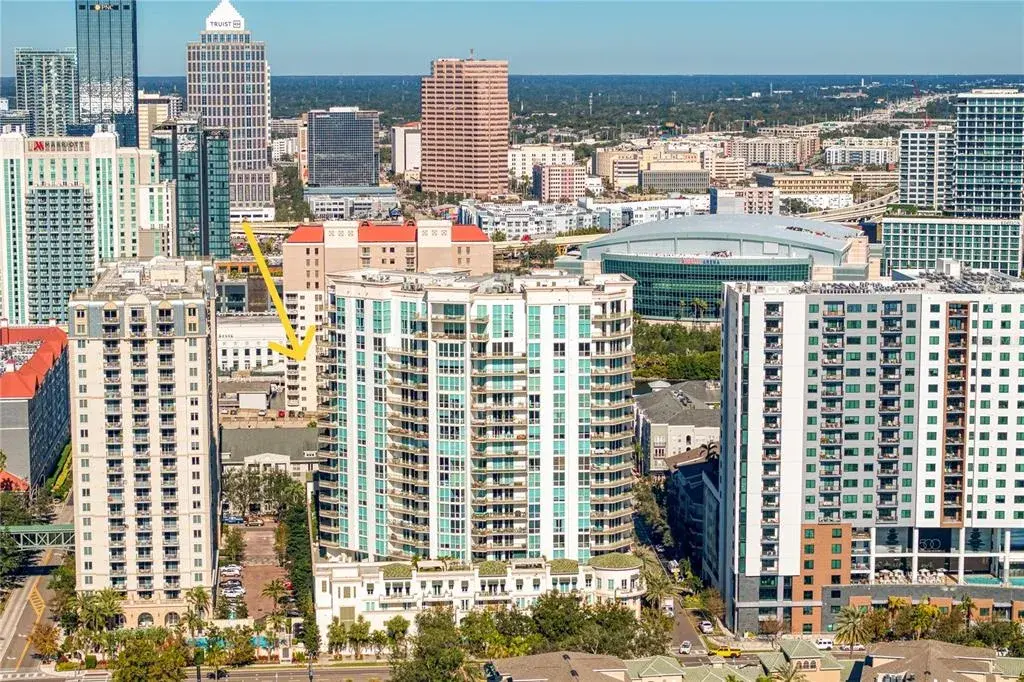
3 bed · 3 bath · 2,400 sqft
$1,270,000
Sold Oct 22, 2026
Our Tampa real estate team helps compare short-sale listings around your property needs and preferred timetable. We organize condition, inspection and documented-status questions alongside ordinary resale alternatives, helping you keep the actual home and written purchase terms central to the decision.
Review Tampa homes for sale and Tampa REO listings as separate purchase comparisons. The short-sale search above keeps its own listing-condition filter.
Gaby Sadler
Property Specialist, Serhant
Tell me your Tampa location, property needs and moving-date flexibility. I'll help compare short-sale listings by the actual home, documented status and ownership costs alongside ordinary resale options.
Your shortlist should reflect more than an asking price. We can help you compare short sales within Tampa's municipal boundary by budget, setting and the property-specific questions that matter to your purchase. Bring your preferred moving date, financing plans and comfort with repairs into that conversation so you can weigh each home against your everyday needs or second-home plans. Use our Tampa guide to explore the broader city search alongside these listings. Whether you continue with a short sale or consider an ordinary listing, start with homes that fit your priorities, then examine the approval stage, condition and contract terms carefully.
 Tampa FL, Homes for Sale & Real Estate1-Bedroom Condos for Sale in Tampa FL1-Bedroom Homes for Sale in Tampa FL